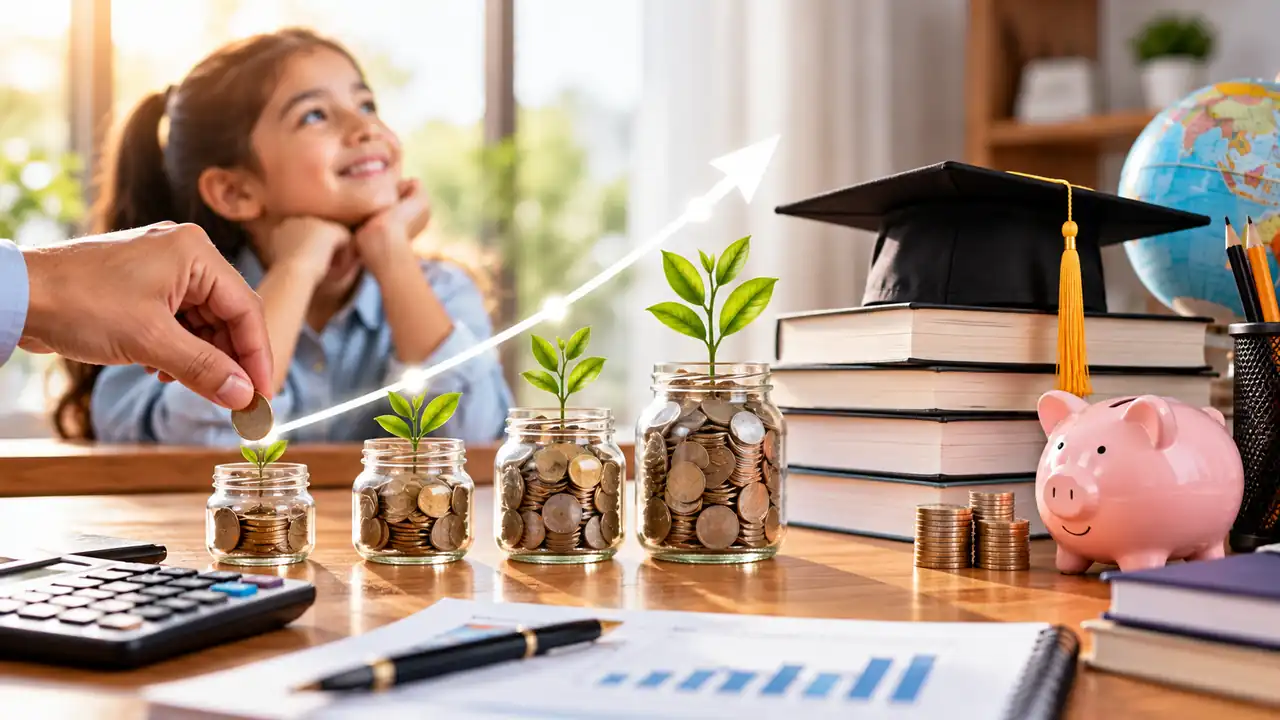
Planning for a child’s education involves estimating future expenses, managing household finances, and building savings over time. With the rising cost of school education, professional courses, and higher studies, parents need a structured approach to prepare for future financial responsibilities. A Systematic Investment Plan (SIP) is one method that allows individuals to invest a fixed amount in a mutual fund scheme at regular intervals.
By starting early, setting realistic financial goals, and reviewing investments periodically, parents can work towards building an education fund while maintaining their other financial commitments. A well-planned SIP strategy can provide a framework for long-term financial planning, although investment returns are not guaranteed and market fluctuations can affect the final amount.
Understanding SIP Investments for Child Education Planning
A Systematic Investment Plan (SIP) allows investors to invest a predetermined amount in a mutual fund scheme at regular intervals, such as monthly or quarterly. Instead of investing a large amount at once, parents can spread their investments over time according to their income and financial capacity.
For example, parents who begin saving when their child is young may have 15–18 years before higher education expenses arise. This extended period can provide more time for investments to grow, depending on the chosen scheme and market performance.
SIPs are not a separate investment product. They are a method of investing in mutual funds. The investment risk, potential returns, and suitability depend on the underlying scheme, which may invest in equities, debt instruments, or a combination of asset classes.
Parents exploring different options can learn about mutual fund investments to understand the available categories, their characteristics, and associated risks before making financial decisions.
Why Early Planning Matters for Your Child’s Education
Education expenses can extend beyond tuition fees. Depending on the course and institution, families may need to account for admission fees, accommodation, books, transportation, technology, examination charges, and other living expenses.
These costs may increase over time due to inflation. Consequently, estimating future expenses rather than relying exclusively on present-day fee structures can help parents develop a more realistic financial plan.
Estimate Future Education Costs
The first step is to identify the likely education path and estimate its potential cost. Parents can consider whether their child may pursue undergraduate studies in India, professional education, postgraduate studies, or education abroad.
The estimate should include both direct and indirect expenses. Since the child’s interests and academic preferences may change, it is useful to prepare different cost scenarios instead of assuming a single fixed outcome.
For instance, if a course costs ₹10 lakh today, its future cost could be substantially higher after 15 years. At an illustrative annual education inflation rate of 6%, the same expense would grow to approximately ₹24 lakh over that period. This is a mathematical illustration, not a forecast of actual education costs.
Determine Your Investment Timeline
The time remaining before the expected education expense is an important consideration when planning investments.
Parents with younger children may have a longer investment horizon, while those whose children are approaching college age may need to prioritise capital preservation and liquidity.
A longer investment horizon does not eliminate market risk. However, it provides more time to make regular contributions and review the strategy as the financial goal approaches.
How to Calculate the SIP Amount for Your Child’s Education
Estimating a suitable monthly SIP requires three main inputs: the target education fund, the number of years available, and the assumptions used to estimate investment growth.
Parents should first calculate the expected future education cost. They can then consider their existing savings and determine how much of the target remains unfunded.
The remaining amount can be used to estimate the monthly contribution required under different hypothetical return assumptions.
Use a SIP Calculator for Goal-Based Planning
A SIP calculator can help estimate the potential future value of regular investments. By entering a monthly contribution, investment duration, and an assumed annual rate of return, users can compare different investment scenarios.
For example, a parent may compare the projected outcomes of investing ₹5,000, ₹8,000, or ₹10,000 every month over 15 years. The calculator can illustrate how contribution amounts, investment periods, and assumed returns influence the estimated corpus.
These projections are hypothetical. Actual mutual fund returns vary, and a calculator cannot guarantee that the final investment value will match the estimated amount.
Parents should also account for existing education savings, other financial goals, emergency reserves, and their capacity to continue contributions during periods of financial uncertainty.
Choosing a Suitable Mutual Fund Category for Education Goals
The choice of mutual fund category should reflect the investment horizon, risk tolerance, financial circumstances, and importance of the future education expense.
Different categories have different investment objectives and risk characteristics. No single category is suitable for every family.
Equity Mutual Funds for Long-Term Goals
Equity mutual funds invest primarily in shares of companies. Their values can fluctuate significantly in response to market conditions, company performance, and broader economic developments.
For parents with a long investment horizon, equity-oriented funds may be one category to evaluate when considering long-term growth potential. However, they also carry the risk of capital loss, particularly over shorter periods or during market downturns.
The suitability of equity investments depends on the family’s ability to tolerate fluctuations and the time available before the money is required.
Debt Mutual Funds for Different Financial Needs
Debt mutual funds invest in instruments such as government securities, corporate bonds, and money market instruments. Their risk and return characteristics depend on factors including credit quality, interest rates, and portfolio duration.
They may be considered when evaluating investment options for particular financial objectives or time horizons. However, debt mutual funds are not risk-free, and their returns are not guaranteed.
Hybrid Mutual Funds for Diversification
Hybrid mutual funds invest in a combination of asset classes, commonly equities and debt instruments. The allocation varies by scheme and may change according to its investment mandate.
These funds can provide exposure to multiple asset classes within a single scheme, but their risk levels differ. Parents should review the scheme’s asset allocation, investment objective, expenses, and risk disclosures before evaluating its suitability.
The choice should be based on the family’s circumstances rather than recent performance alone.
Creating a Step-by-Step SIP Strategy for Child Education
A structured approach can make education planning easier to manage and review.
Step 1: Define the Education Goal
Identify the approximate age at which the funds may be needed and the type of education expense being planned. Estimate the cost using current information and account for potential inflation.
Step 2: Calculate the Funding Gap
Subtract existing education savings and other earmarked funds from the estimated future requirement. This provides a preliminary target for additional savings and investments.
Step 3: Assess Your Monthly Budget
Review household income, essential expenses, insurance premiums, loan repayments, emergency savings, and other financial obligations.
Determine an investment contribution that can be maintained without compromising essential expenses or creating excessive financial pressure.
Step 4: Evaluate Suitable Schemes
Compare mutual fund schemes based on their investment objectives, asset allocation, risk indicators, expense ratios, historical performance across different market conditions, and other relevant disclosures.
Historical performance does not establish future returns. Scheme selection should reflect the investment goal and the investor’s risk tolerance.
Step 5: Set Up Regular Contributions
A monthly SIP can help establish a consistent investment routine. The contribution date and amount should fit the household budget.
Investors should also understand the applicable scheme terms and the implications of missed instalments, discontinuation, or redemption.
Step 6: Review the Plan Periodically
Education planning requires ongoing attention. Parents can review the target amount, savings progress, contribution affordability, and investment allocation at regular intervals.
Reviews are particularly useful when household income changes, education preferences become clearer, or the expected cost of the course increases.
Managing Inflation and Increasing Education Costs
Inflation can reduce the purchasing power of money over time. An education fund that appears sufficient based on today’s expenses may not cover the same course in the future.
To account for this possibility, parents can calculate the projected future cost under multiple inflation assumptions.
For example, a current education expense of ₹15 lakh would rise to approximately ₹35.9 lakh over 15 years at an illustrative annual inflation rate of 6%. At 8% annual inflation, it would rise to approximately ₹47.6 lakh.
These figures demonstrate how different assumptions can affect the financial target. They are not predictions of future education inflation.
Parents may also consider reviewing their contributions as income increases, provided the revised amounts remain affordable. Periodic increases in contributions can help address a growing funding gap, but they do not eliminate investment risk or guarantee that the target will be reached.
Reducing Investment Risk as the Education Date Approaches
One important aspect of education planning is managing the risk of a market downturn shortly before the money is required.
A portfolio exposed heavily to market fluctuations may experience a decline at an inconvenient time. If the investment must be redeemed to pay tuition or admission fees, a temporary fall in value can affect the available funds.
Parents can review their asset allocation as the education date approaches and evaluate whether a gradual shift towards less volatile or more liquid options is appropriate.
The timing and extent of any adjustment depend on the remaining investment horizon, the amount already accumulated, and the family’s financial circumstances. Moving investments between schemes may also have tax implications or exit loads, depending on the applicable rules and scheme terms.
Maintaining a separate emergency fund can help reduce the need to redeem education investments unexpectedly to meet unrelated household expenses.
Common Mistakes to Avoid When Planning an Education SIP
Even a consistent investment routine can fall short of its objective if the underlying plan is unrealistic.
Some common mistakes include:
- Starting without a defined target: Investing regularly without estimating future education expenses makes it difficult to assess whether the contributions are sufficient.
- Ignoring inflation: Using today’s education costs without projecting future expenses can result in an inadequate target.
- Assuming guaranteed returns: SIP investments in mutual funds are subject to market risks, and projected returns may not materialise.
- Choosing schemes based only on recent returns: Short-term performance does not necessarily indicate long-term suitability.
- Ignoring other financial priorities: Education planning should be balanced with emergency savings, insurance, retirement planning, and existing liabilities.
- Failing to review the investment: Changes in income, family needs, and education costs may require adjustments to the strategy.
- Taking excessive risk close to the goal: A significant market decline shortly before the funds are needed can affect the amount available for education.
Addressing these issues can help families maintain a more realistic and disciplined approach to their financial goals.
Tax Considerations for SIP Investments
Tax treatment is another factor to consider when evaluating mutual funds for education planning. The applicable tax rules depend on the fund’s classification, the nature of the capital gains, the holding period, and the prevailing tax regulations.
Each SIP instalment is generally treated as a separate investment for determining its holding period. Consequently, units purchased on different dates may receive different tax treatment when redeemed.
Parents should also understand that tax-saving provisions do not automatically apply to every mutual fund. Eligibility depends on the specific investment and the relevant statutory requirements.
Since tax rules can change, investors should verify the applicable provisions before making redemption decisions. A qualified tax professional can help clarify the implications for individual circumstances.
Conclusion
Planning for a child’s education through an SIP investment strategy involves more than selecting a mutual fund and deciding on a monthly contribution. It requires estimating future expenses, accounting for inflation, understanding investment risks, assessing affordability, and reviewing progress towards the financial goal.
Starting early may provide more time to build savings through regular contributions, while periodic reviews can help parents respond to changes in education costs and household circumstances. A SIP calculator can support initial projections, and an understanding of different mutual fund categories can help investors evaluate available choices.
The central objective is to build a realistic, flexible education funding plan that reflects the family’s financial capacity and the child’s potential future needs. Investment decisions should be based on individual circumstances, risk tolerance, and verified information rather than assumed returns or a fixed expectation of market performance.
Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing.