This is mostly because it takes people years to develop a nest egg, but not nearly as many people consider how to utilize one. You probably don’t want to get it all in one go, and it won’t do you any good just sitting there. Before you start, an SWP calculator can tell you where the middle ground lands. A methodical withdrawal strategy is a way to get there.
What is SWP in a Mutual Fund?
An SWP simply means you may withdraw a certain amount from your mutual fund at an interval that you choose (typically monthly). The balance of your money will stay invested and make you money. SWP is a good option for those who are short on cash or retired to invest in mutual funds without selling all of their stock.
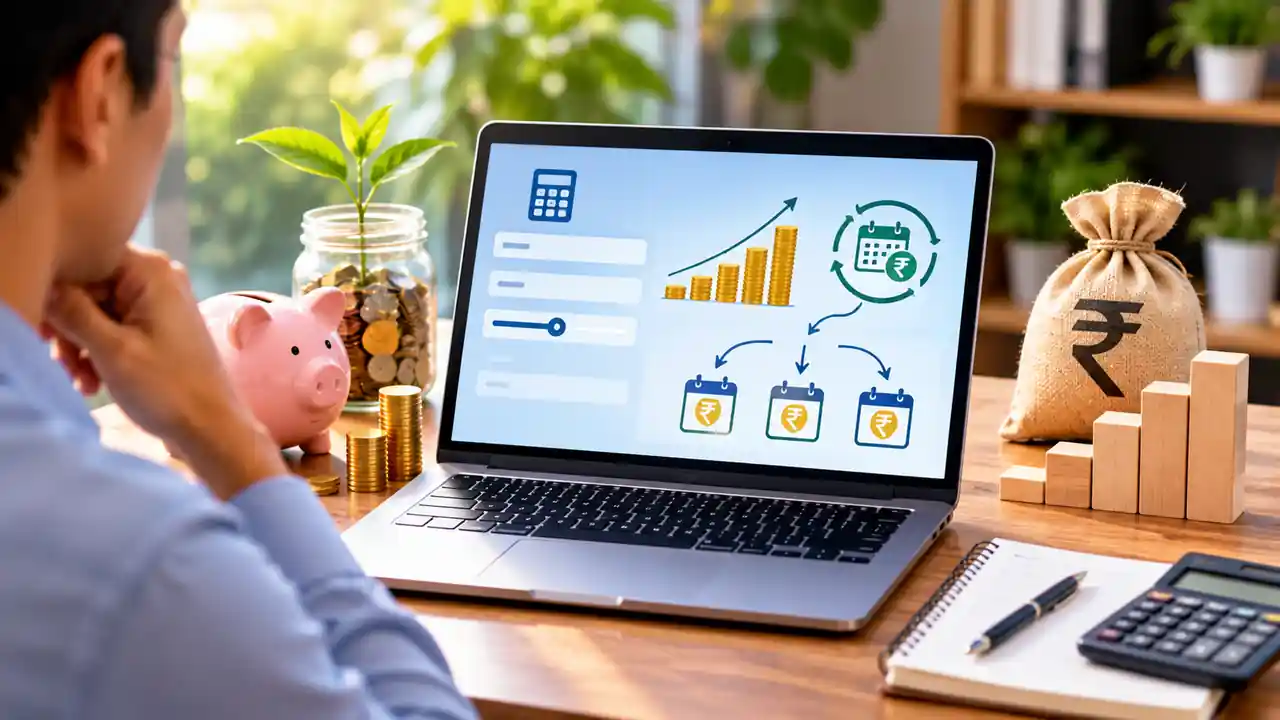
A SWP Calculator can help you see how this approach may function. It tells you how much you will have in the end, depending on your investment, your monthly withdrawal, an expected return, and the duration you stay invested. It isn’t trying to predict what the market will do, but to assist you plan.
What Goes into the Calculator
What You Put in the Calculator There are four things it all comes down to:
- Investment amount: The lump sum you start with.
- Monthly withdrawal: The fixed amount you want to take out each month.
- Expected return: The average yearly return you assume on the remaining balance.
- Time period: The number of years you plan to keep withdrawing.
These factors together might affect the outcome, therefore you might want to test a few variations of these factors before you settle on a strategy.
How the Calculation Works in Plain Words
There are usually two things that get done each month. First, they extract the exit, and then the rest receives the projected yearly return for the month. The rest goes to the following month.
Here is a little photo. Now imagine that you have ₹10,00,000 and you make 1% each month from it and withdraw ₹5,000 each month. In the first month, the amount goes up to ₹1,01,000 then down to ₹96,000 when you withdraw the money. The balance rises up to ₹96,960 in the second month and then down to ₹91,960 in the third month. Every month we are taking out more than we are adding to the balance itself, that’s why it’s just going down. If the increase were more than the money being taken out, then the balance would be increasing, not decreasing.
Benefits of Checking the Numbers First
A few practical gains stand out:
- Clear amount of your return: you see how much you can make each month and how long.
- Investing with a lower return: You have to see whether your strategy stands up to a reduced rate of return.
- Comparison: You are able to set various withdrawals up to compare side by side.
- Less guessing: A calculator removes guesswork out of your thoughts and puts down a reliably successful approach.
- Better conversations: A good financial adviser will lead to a good, cohesive discussion about plans.
Worked Examples in ₹
The figures assume withdrawals at the end of each month, a constant return and no taxes or fund costs. They are rounded and meant only for illustration.
₹10,00,000 With ₹8,000 a Month for 10 Years
- Assumed return: 8% a year
- Total withdrawn: ₹9.60 lakh
- Estimated balance left: about ₹7.56 lakh
₹25,00,000 With ₹20,000 a Month for 15 Years
- Assumed return: 7% a year
- Total withdrawn: ₹36 lakh
- Estimated balance left: about ₹7.83 lakh
In the second plan, when you withdraw more than his installments yet have some surplus. This is feasible because the money you have invested accrues interest, and portion of that interest goes to part of the cost of each withdrawal.
What Can Change Your Result
Sometimes we and reality don’t quite jell with the estimates. The SWP returns, with the mutual fund strategies, are as good as the assumptions behind them. Here are several factors that impact SWP projections:
- Market returns: Actual returns vary from year to year and may be lower than assumed, especially for equity-oriented funds.
- Withdrawal size: A larger withdrawal drains the balance faster.
- Fund costs: The expense ratio reduces what your investment earns.
- Taxes and exit load: These may apply when units are sold, so check the rules for your fund.
- Timing: A market fall early in the plan hurts more, because units are sold at lower prices.
Who Can Use an SWP Calculator
If you wish to gradually draw money from a lump amount, it’s good for you. It provides monthly income to pensioners. There is a person who obtains a check or money from that transaction and then spreads that money across years. Others utilize for things they must do continuously like yearly fees paid monthly. It verifies in each situation whether the payment amount is in accordance with the intended departure.
Mistakes to Avoid
- Assuming a very high return to make the plan look sustainable.
- Choosing a withdrawal that is too large for the size of the corpus.
- Treating the monthly amount as guaranteed income.
- Never reviewing the plan after it starts.
Choosing Where to Invest
It doesn’t choose your fund. Your risk level and your gain stability will be dependent on the sort of fund that you have. Knowing the sorts of mutual funds can help you pick one that fits your income demands and your tolerance for swings. Before you start an exit plan, read the plan’s regulations and know the cost.
Final Thoughts
An SWP may convert your nest egg into income you can draw on regularly, but you need to do the math to see how well the plan holds up. Test the proper annual withdrawal using the calculator and do it each year. Returns are not guaranteed, so include some wiggle room into your strategy. A conservative prediction now is much better than a nasty surprise later.


